Bolton, MS
Bolton Life Insurance, Reviewed Every Year
People in Bolton, Clinton and Jackson count on us for term life, whole life, universal life, final expense and mortgage protection coverage, and we keep looking after the policy once it takes effect. We schedule a yearly review for you, confirm your beneficiaries each year and hand you a single page showing what you hold and what it covers.
- Property & Casualty license
- Variable Life & Variable Annuity license
- Working in insurance since 2016
- We book your yearly review
Life Insurance Coverage We Set Up
Our work in the insurance industry goes back to 2016, and the licenses behind it are a Property & Casualty license plus a Variable Life & Variable Annuity license. The variable license is what allows us to offer variable life insurance, since that policy's cash value is held in market subaccounts and is sold as a securities product. Alongside it, we write term life for income replacement, whole life and universal life for permanent coverage, final expense insurance for funeral and end-of-life bills, and mortgage protection sized to the balance on your loan. Each page below explains how that policy is built and what moves its premium.
Term Life Insurance
Level-premium term life for the years your family depends on your income, with conversion dates and beneficiaries tracked after the policy is issued.
Whole Life Insurance
Permanent coverage with a level premium and cash value that grows inside the policy, plus a yearly check-in so it keeps matching your family.
Universal Life Insurance
Permanent coverage with adjustable premiums and a cash value account, plus a yearly review we schedule so the policy stays funded.
Final Expense Insurance
A small permanent policy sized to cover funeral costs and final bills, with health questions explained up front and a yearly check-in after.
Mortgage Protection
Life insurance sized to your home loan and paid to your beneficiaries, so your family decides how to keep the house.
Variable Life Insurance
Permanent coverage with cash value invested in subaccounts you pick, explained line by line and checked with you every year.
How Getting Covered Works
We talk in plain terms, explain every option and let your family decide on its own schedule.
- 1
Phone us for a free quote
You reach a person, not a machine. We ask your age, your health, whether you use tobacco and what income or debts need covering, then give you a quote at no charge.
- 2
Sit down by video or in our office
When you want a closer look, we meet over video or at our office. We lay term, whole and universal coverage side by side and show how each treats premiums, cash value and length of coverage.
- 3
The application and carrier review
During your appointment we answer the application questions together and tell you what the carrier will check. Some policies need a paramedical exam at your home or job, while others are approved from records alone. We keep you posted until the carrier decides.
- 4
Your policy and one-page summary
Once approved, we meet to walk through the issued contract page by page. We confirm every beneficiary name is spelled and listed the way you want, then hand you a single sheet that sums up your coverage.
- 5
A yearly review
About a year on, we reach out to set your review, and we repeat that every year so your coverage matches the life you have today.
Your Agent Next Year and Every Year After
Life Insurance Bolton is a local agency serving individuals and families who want their coverage set up with care and kept up to date. Call us and a live person answers, the same agent you will be working with for years to come.
Every plan we put together is personalized to your needs and your budget. For some people that is one term policy. For others it is a modest whole life policy for long-lasting needs alongside term coverage for the years when the kids are at home and the mortgage is high. We tell you the reason behind each part, and we never steer you toward more coverage than you need.
- License
- Property & Casualty license; Variable Life & Variable Annuity license
- In business
- In the insurance industry since 2016
Why Our Clients Stick With Us
A lot of life insurance is sold one time and never reviewed. A 2018 policy might still list an ex-spouse, leave out a new child or come up short against a larger mortgage, and no one catches it until there is a claim. Our attention goes to the years after you sign.
A yearly review we schedule
Each client has a review every year, and we take care of booking it. We hold your coverage up against your current debts, income and household, and if nothing needs to change, we say so.
Beneficiaries reviewed each year
Every year we go over who your beneficiaries are. A policy designation overrides a will, so an old name or a minor named without a custodian can send the money where you never meant it to go.
Updates inside a week
New baby, new house, new job? Tell us, and we adjust your coverage within a week of your call. It could be a quick beneficiary form, or a rider or extra term policy added to what you already have.
Your coverage on one sheet
Policy contracts can stretch to dozens of pages. We give you a single sheet showing each policy, what it costs and the people and debts it protects, so your spouse can find answers without searching through the contract.
Beside your family at claim time
Your family never files a claim alone. We take them through it ourselves, from the death certificate to the claimant statement the carrier asks for.
What Drives Your Premium
Your premium is the carrier's risk estimate divided across the years you pay. A handful of details do most of the work, and they explain why two quotes for the same coverage can differ so much.
Quotes are free and come over the phone after a brief talk about your age, your health and what you want to protect. We go over each number with you before you make any decision.
- Your age at application
- The rate is set by your age on the day the policy is issued, and level term keeps that rate for the whole term. Applying at 35 instead of 45 can noticeably lower the price for the same length of coverage.
- Your health and rate class
- The underwriter looks at your prescriptions, your medical records and at times a paramedical exam with blood pressure and lab work. That review puts you in a rate class, which affects the price more than nearly anything else.
- Nicotine and tobacco
- Smoking, vaping and certain nicotine products place you in a tobacco class. Most carriers want at least a year without use before they offer non-tobacco rates.
- Type of policy and length of term
- Term coverage stops after a set number of years and has no cash value, so the premium stays low even on a large face amount. Whole life and universal life cover you for life and direct part of each payment to cash value, which makes them cost more.
- Face amount and riders
- The face amount sets the starting price. Riders like a waiver of premium, a child term rider or an accelerated benefit for terminal illness each carry a separate charge, and we show you every one so you can judge whether it is worth paying for.
What Our Clients Want to Know
Something not covered here? (601) 286-2593
Is term life or whole life right for me?
Term life covers a set period, usually 10, 20 or 30 years, and pays only if death occurs during it. It fits needs that end, such as a mortgage or raising kids. Whole life lasts your entire life and builds cash value at a guaranteed rate, which makes it pricier. Many families combine term for big short-term needs with a smaller permanent policy for final expenses.
How do you figure out how much coverage I need?
We begin with what you owe, starting with the mortgage. Then we add the years of income your family would need replaced, plus costs such as college or a funeral. Finally we subtract your savings and any coverage from work. That total is what we quote, not a rounded number that drives up the premium.
Is a medical exam required?
That depends on your age, the amount of coverage and the carrier. Some policies are approved from prescription history and medical records alone. Bigger amounts often call for a brief paramedical exam at your home or job that checks blood pressure, height, weight and lab samples.
How does a claim work for my family?
They contact us, and we take them through each step ourselves. We help collect the death certificate and the carrier's claim form, and we keep following up with the carrier until the money is paid. If death happens within the first two years, the carrier may look back at the original application, which is why honest answers matter.
Can I update my beneficiaries down the road?
Yes. Most policies let you change beneficiaries whenever you like using a carrier form. We review them with you every year and update them any time you tell us about a marriage, a divorce or a new child.
Do I have to come to Bolton to work with you?
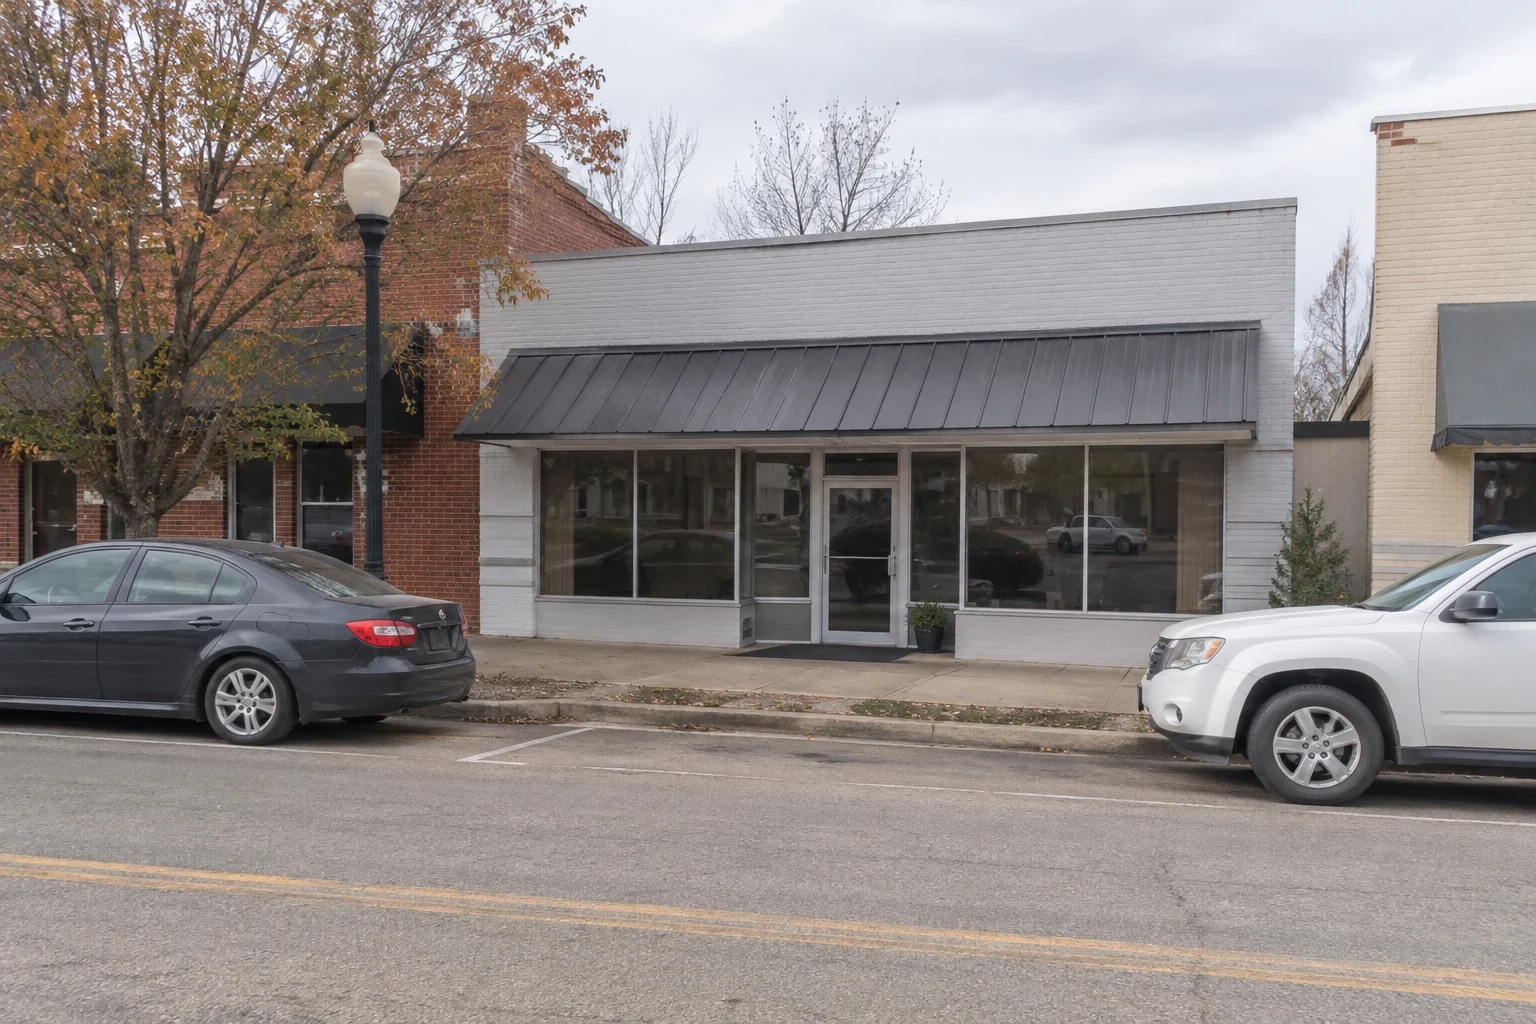
No. Virtual appointments are available, and plenty of clients handle everything from the first quote to signing the policy by phone and video. If you prefer to meet in person, you are welcome at our Bolton office.
How soon can I get a quote?
We get back to you and quote the same day. A short call covering your age, your health and what you want to protect tells us what we need, and there is no charge for the quote.
Where Our Clients Live Around Bolton
We are based in Bolton and work with people throughout Hinds County and nearby, including Clinton, Jackson, Byram, Pearl, Flowood, Richland and Vicksburg. Above Jackson, we also serve Ridgeland, Madison and Beechwood. With virtual appointments available, the drive is never a reason to wait.
- Bolton
- Clinton
- Jackson
- Ridgeland
- Byram
- Madison
- Richland
- Beechwood
- Pearl
- Vicksburg
- Flowood
Live in Mississippi but not in one of these towns? Ask us on the phone. In most cases we can help you by phone and video.
Start With a Free Quote, Then Let Us Keep Watch
One phone call gets you a free quote and an honest look at which policy fits. After that, the yearly reviews are on us to schedule.